ArticleBy Matvei Kostiuchenko
Corporation Tax: you pay before you file
Your Corporation Tax is usually due three months before your CT600. How the two deadlines work, with dates for a 31 March year end.
Most directors assume the tax is paid when the return goes in. For Corporation Tax it is the other way round: for most small companies the payment is due three months before the Company Tax Return (CT600). Miss that and HMRC starts charging interest while you still think you have plenty of time.
Two deadlines, one accounting period
Both dates count from the end of your company's accounting period for Corporation Tax. That period usually matches the financial year of your accounts, and it can never be longer than 12 months.
- Payment: 9 months and 1 day after the end of the accounting period.
- CT600 to HMRC: 12 months after the end of the accounting period.
The payment date applies to companies with taxable profits up to £1.5 million. Larger companies pay in quarterly instalments instead, and the £1.5 million limit is shared out if you have associated companies.
An example: year end 31 March 2026
| Deadline | Due | Counted as |
|---|---|---|
| Accounts to Companies House | 31 December 2026 | 9 months after year end |
| Corporation Tax payment | 1 January 2027 | 9 months and 1 day after |
| CT600 to HMRC | 31 March 2027 | 12 months after |
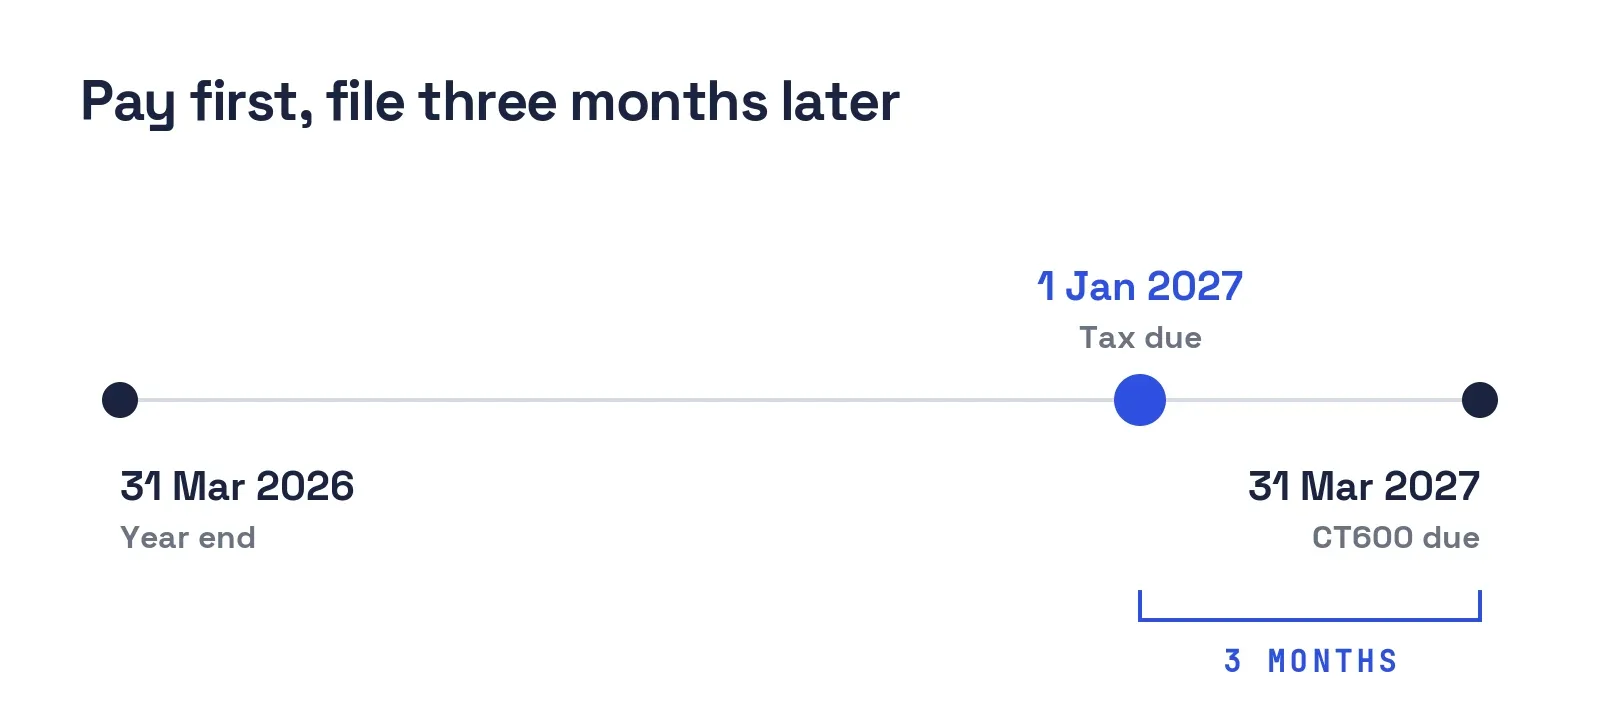
Deadline: For a 31 March 2026 year end, the tax is due on 1 January 2027 — a bank holiday, so pay before it. The return can wait until 31 March 2027, but you need its figures to know how much to pay.
Companies House has its own date for the accounts: 9 months after the end of the financial year for a private company, or 21 months after incorporation for the first accounts. It is a separate obligation with separate penalties.
What happens when you are late
Paying late. HMRC charges interest on unpaid Corporation Tax from the day after the payment deadline until the day it is paid. There is no grace period.
Filing late. Penalties for the CT600 build up over time:
- 1 day late: £100.
- 3 months late: another £100.
- 6 months late: HMRC estimates your tax bill and adds a penalty of 10% of the unpaid tax.
- 12 months late: another 10% of any unpaid tax.
If a return is late three times in a row, the two £100 penalties become £500 each.
A company with no tax to pay still has to file if HMRC has sent it a notice to deliver a return. The deadline and the penalties are the same.
How to stay ahead
- Prepare the return early, before the payment date, so you pay the right amount rather than a guess.
- Pay using the payment reference for that accounting period, not the reference from last year: HMRC matches payments by it.
- Put both dates in your calendar the day your year ends. In filefast they appear on the company page, with a reminder before the payment is due.
Sources: Pay your Corporation Tax bill and Company Tax Returns: penalties for late filing on GOV.UK.